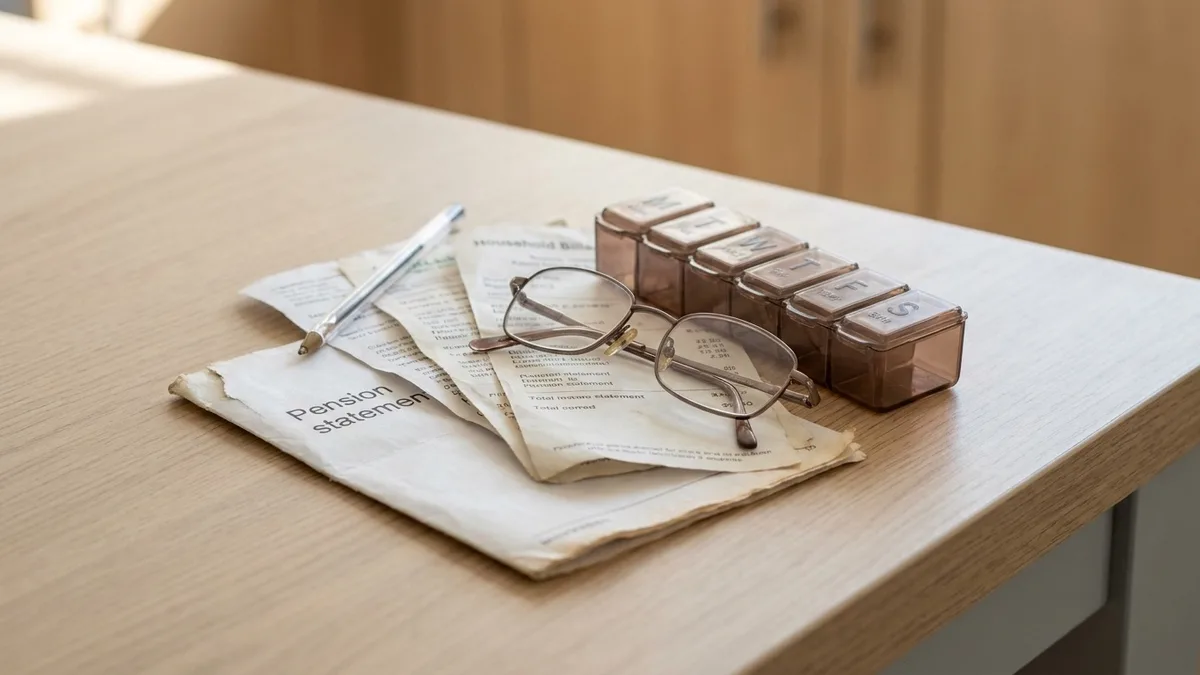
Retirement math, people assume, is the whole story behind claiming Social Security early. Get the numbers wrong at 62 and you pay for it. That assumption misses what the regret is actually made of, because around 75 the filing decision is not the thing that changed. Everything else did.
The check that looked adequate a decade ago was set in place years earlier and never moves except for cost-of-living adjustments. The budget it has to cover at 75 is a different budget: property tax and homeowners insurance that keep climbing, Medicare premiums taken out before anything else, and out-of-pocket medical costs that arrive in clusters rather than as a steady monthly figure. Someone who filed at 62 may be living on $1,720 a month after adjustments, while a peer who waited until 65 brings in $2,050, and the gap between those two numbers is only part of why the later years feel tight.
So the claim itself may be settled. The gap it leaves is not one thing: part of it is chronic and predictable, part of it is shock-driven, and a real slice of it can still be adjusted. Sort those pieces and you stop reliving the filing decision.
You will leave able to place your own gap in the right category, build a three-number budget, and make one call this week.
The check stops growing when costs don't
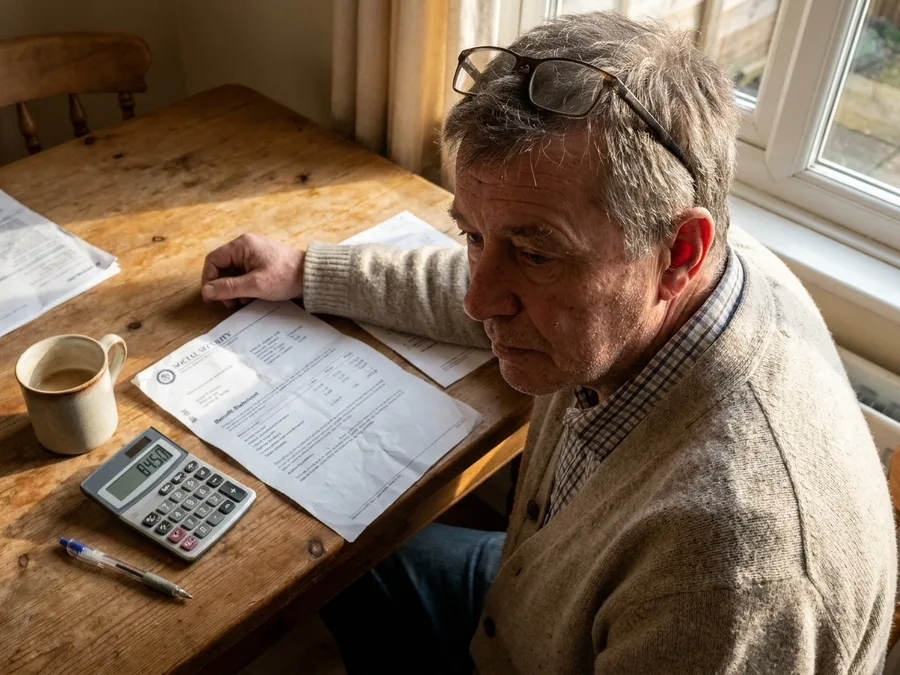
The squeeze you feel is not imagination and it is not the same as a bad decision. Pat is 75, claimed at 62, and now draws $1,720 a month after the annual cost-of-living adjustments; Jim waited until 65 and draws $2,050. When Pat talks about the check feeling smaller than it used to, the difference is real, and it lives in the gap between those two numbers, not in the calendar.
The claim set the base, and the base does not move upward later. Starting Social Security earlier locks in a lower monthly amount that the yearly adjustments only nudge forward; the exact reduction depends on the earnings record, so SSA is the place to get your own precise figure rather than a rule of thumb.
Now subtract what the household actually pays. Medicare Part B and the supplement run $540 a month for the couple, and out-of-pocket medical costs average $220 — both household totals, not per person. Against Pat's $1,720 alone, that leaves $960 before housing, food, utilities, or a single other bill.
This is a chronic mismatch, not a sudden crisis: a fixed, lower benefit base meeting fixed costs that arrived afterward and moved upward. The same early-claim amount plays out very differently when a pension, a bigger savings draw, or a spouse's full benefit sits underneath it and absorbs the pressure.
The adjustable edge is the medical line, not the past decision. Your premium and out-of-pocket spending are the only parts of this month you can still rework, and reworking them is where the next section begins.
Health costs arrive in clusters, not averages
The $220 a month is a smooth number, and smooth numbers hide the trouble. That figure is prescriptions and copays in the ordinary months, not a year with a surgery in it.
Then a knee goes. Pat's replacement left $2,300 out of pocket after insurance settled, and the bills landed in the mailbox over a few weeks while the monthly budget was still running on the old assumption.
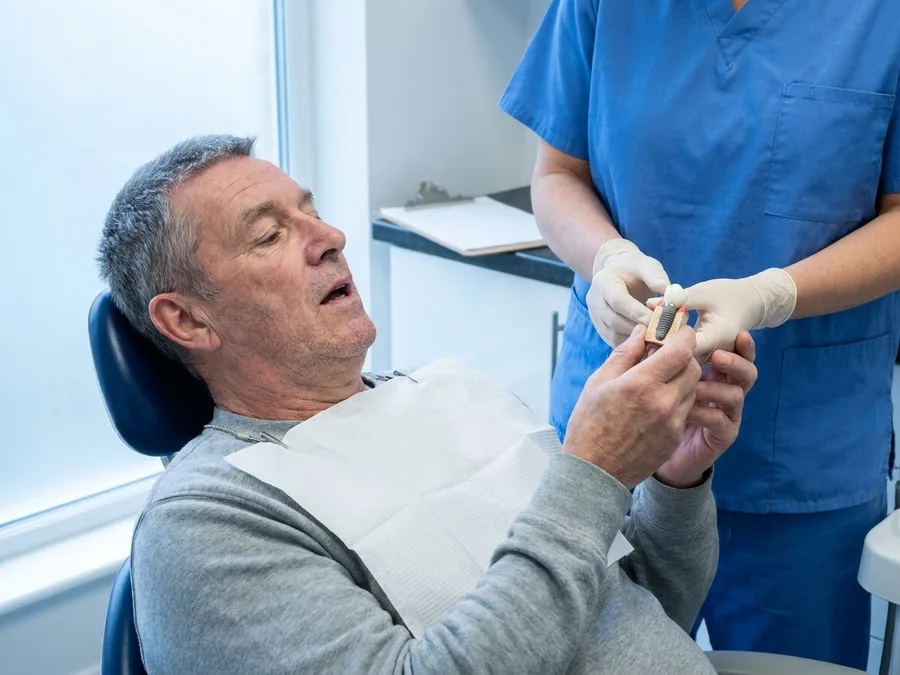
The dentist was already on the calendar. The implant quote came back at $4,800, and both numbers together reach $7,100 – money the $220 line was never built to carry. Covering it means pulling from the $62,000 in savings or changing the plan.
The timing is what breaks people. Surgery, the prescriptions that follow, the dental work that was put off, the extra rides to appointments and the grab bars at home – they can all land inside one quarter, before a monthly budget has any chance to reset.
Some households have a cushion for exactly this: retiree coverage from an old employer, an HSA funded during working years, or savings set aside for medical years. If that exists, the cluster is uncomfortable rather than destabilizing.
This is why the regret so often gets dated to the wrong event. The tearful story usually starts at the surgery, not at the claim. The one-time hit and the chronic premium-and-copay base underneath it are two different problems, and only one of them is about the year you filed.
⚠️ COMMON MISTAKE
Don't judge the claim by the surgery year
A single $7,100 cluster of surgery and dental work can make the whole early-claim decision feel wrong. Separate the one-time hit from the $540 monthly premiums and $220 copays. The cluster is a savings question; the monthly base is a coverage question. They need different answers.
Housing eats the cost-of-living increase
The cost-of-living raise gets swallowed by housing before it reaches groceries. A paid-off mortgage is real relief, but owning the house outright does not take housing out of the monthly picture.
Property tax and homeowners insurance together come to $460 a month in this household – a fixed bill that arrives whether or not anything is owed on the house. When the annual increase lands, it meets a property tax bill that has its own trajectory.
Insurance premiums climb after storm years. Repairs do not wait for a convenient season. The raise can go entirely to those three lines and never touch everyday spending, which is why the check feels flat even in a year the letter said it went up.
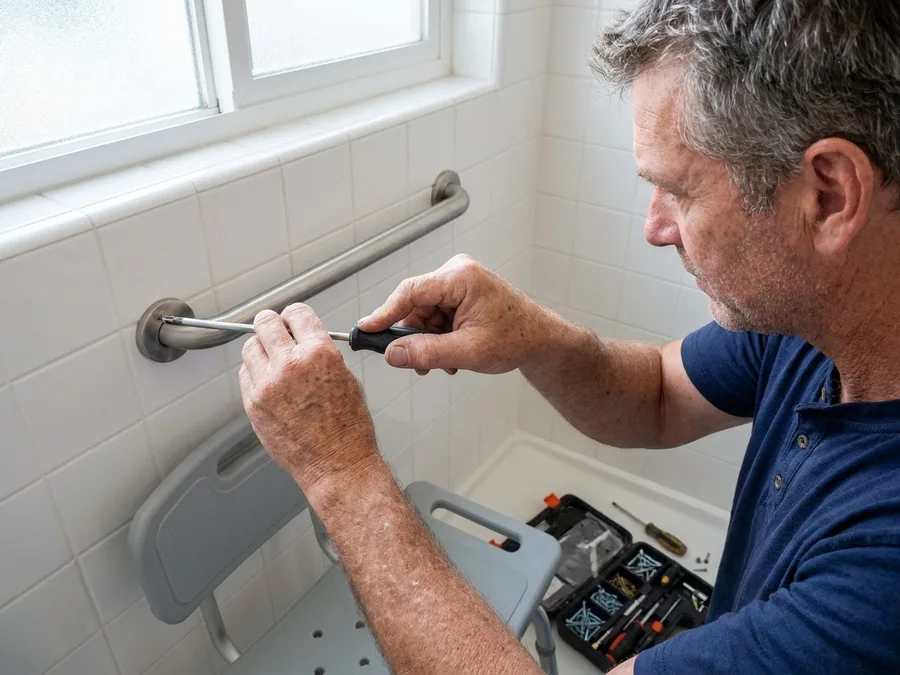
Aging adds its own housing costs, and they arrive dressed as safety rather than maintenance. A bathroom grab-bar and shower chair update runs $650, and it surfaces the month someone wobbles in the shower – not the month anyone planned for a home project.
Location is the quiet variable here. The same house in a low-tax county, or a daughter who can handle repairs on a weekend, changes how hard the same erosion bites. Family help with a repair is worth as much as a raise.
Housing is mostly a chronic line, and the $650 is a one-time hit that sits on top of it. The adjustable edge is narrow but real: check whether any benefit or local program helps with property tax relief or a home-safety modification before paying either out of savings.
Part-time work ends earlier than planned
The small job was never part of the retirement math. It was the line that made the lower check work, quietly covering the same housing costs that never go away.
Pat's $700-a-month bookkeeping work ended at 74, a year after a knee replacement made the hours impossible to keep. The surgery cost $2,300 out of pocket. Start the arithmetic and the month is short $700 plus $2,300, and the household budget was never reset to match. It kept running as if the deposit still came.
The pattern repeats often enough to count on: a part-time job carries the early-claim budget into the early 70s, then a health event ends it and the fixed costs stay put.
Some income can still come back. Contract bookkeeping done from a kitchen table, fewer hours instead of none, or a spouse who keeps working a few more years all leave something flowing.
The useful question is not how to replace the job. It is which expenses were built around that $700 and which of them can be renegotiated, reduced, or carried from somewhere else. Lost income is both a single hit and a permanent subtraction, and each needs its own answer.
The early-claim budget stack
What sits on top of a fixed benefit, from foundation to squeeze
One death can cut two checks to one
Two checks become one, and the survivor keeps the larger of the two, not the sum. The household income does not simply lose half; it falls to a single base overnight.
In the example, Pat's $1,720 and Jim's $2,050 go from $3,770 total to a survivor benefit SSA confirms. The $540 Medicare premium total and the $220 medical figure do not shed half their weight easily either, since some of it follows one person. Rent or property tax, utilities, and food stay sized for two people. A single deposit against two-person costs is how a month that worked became a chronic gap.
Widowhood is a shock to the income base, not a slow erosion. That distinction matters because the fix is different: survivor options get confirmed with SSA first, before anyone trims medication, drops dental visits, or cancels the $650 bathroom update. A pension, life insurance, or adult children close by can soften the same drop, but they are not assumed.
Caregiving drains cash and time at once
Because caregiving spends two currencies at once – cash and hours – and it usually starts while the early-claim budget is at its tightest. Helping a spouse, a parent, or a grown child adds travel, home changes, and unpaid time that shows up nowhere on a statement.
The $650 bathroom update – grab bars, a shower chair – is exactly the kind of cost that appears for a spouse or a parent, not just for your own home. One setup is manageable; the same setup followed by ongoing transport and home-help is a new monthly line.
The hours bite harder than the cash. Caregiving can pull you away from paid work, so the $700 bookkeeping job becomes the kind of income that quietly gets harder to keep as care hours rise. That is a chronic loss dressed up as a temporary stretch.
Partial relief exists. Paid family leave, hired caregivers, or nearby relatives can carry part of the load, and the point is to arrange that help before you drop care – or a job – to do it all yourself.
Sort the shock from the steady drain. The one-time $650 is a hit; the transport and home-help that follow are monthly, and those are the lines to solve with paid or family support rather than your own unpaid hours.
💡 PRO TIP
Call the local senior center before you pay a driver
Many towns run discounted ride programs for medical appointments. One call can turn a paid transport line into a small copay. Ask specifically about medical transport and grocery delivery vouchers, not general senior services.
Isolation leaks money through small errands
Staying home is not the cheap option it looks like on paper. Once driving gets harder, the errands don't disappear, they just get a price tag attached to someone else's car. Delivery fees, paid rides, a hired hand for the gutter or the faucet, and small health purchases that never arrive as one clean medical bill all start landing on the same month.
The adult daughter covers some of the rides, and that is a real help. It is also not a schedule you can build a budget on. When she can't, a paid ride does the job at full price.
The $650 bathroom update is the clearest example of how practical help becomes a line item. Grab bars and a shower chair are not medical care and they are not routine maintenance either. They are what lets a person keep washing without help, and they have to be bought or arranged.
None of this is a story about loneliness. It is a cost pattern, and it behaves differently from a medical premium. The transport and delivery money is chronic, showing up a few dollars at a time every week. The home safety setup is a one-time hit you either absorb now or pay for later in a different form.
That split is where the adjustable edge sits. A walkable neighborhood, a senior center van, or a county transport service keeps the chronic line smaller, and local agencies sometimes help with the one-time safety items. Worth a call before you assume the errands have to stay expensive.
Chronic gap vs. one-time shock
Chronic monthly gap
- $540 monthly Medicare premiums
- $220 average out-of-pocket medical
- $460 property tax and insurance
- $700 lost part-time income
One-time shock
- $2,300 knee replacement out-of-pocket
- $4,800 dental implant quote
- $650 bathroom safety update
- A cluster can total $7,100 in one quarter
The claim cannot be undone, the plan can
For most people reading this, there is no reversal to find, and the time spent hunting for one is time not spent on the parts that can move. Pat's $1,720 and Jim's $2,050 are set. Those figures are the floor the month starts from, not a lever.
The rules on withdrawal and suspension do exist, and SSA is the only source that matters for whether any of them apply to you, what the deadlines are, and what eligibility looks like in your case. This article won't state those rules because a wrong number here costs you real money.
Here is the case worth checking. A claim filed very recently, or a work record with unusual gaps or earnings, can behave differently than the standard picture, and that is a question for SSA directly rather than a reason to assume the door is shut.
What is genuinely adjustable is the other half of the month: the $540 in Medicare premiums, the $220 in medical costs, the $460 in property tax and insurance, and the $700 in bookkeeping income that stopped at 74. Those are the numbers that changed after the claim, and they are the numbers that can still change.
So the sequence matters. Sort what is fixed from what is adjustable, and put your effort on the adjustable side. That means a benefits checkup on coverage and cost before anyone touches a prescription or skips a dental visit to make the month work.
A benefits checkup finds money already there
Money is often already sitting there in a benefit or a better-fitted plan, and the check is free. Start with SHIP, SSA, and Medicare. Those three are where the actual eligibility numbers live, and this article deliberately doesn't quote income cutoffs or thresholds because the numbers change and a stale figure can send you down the wrong road.
The first two lines to put in front of a counselor are the $540 Medicare premium total and the $220 in out-of-pocket medical costs. Ask directly whether a different plan fits your prescriptions and your doctors better, and whether any extra help applies to the premium itself.
Then widen it. State and local programs sometimes cover a piece of what Medicare doesn't, from drug costs to home safety. The timing matters here more than people expect. Do this check before you drop a prescription, cancel a dental visit, or put off the grab bars.
Readers with higher incomes may hear a string of no's on need-based help, and that is a legitimate outcome. A SHIP counselor can still review plan fit, which is often where the real savings sit regardless of income.
A checkup converts a vague worry into a number either way: found money, or a confirmed no you can stop chasing. Either result is more useful than another year of wondering.
What the regret is really about
The fixed part is the claim. The adjustable parts are coverage, budget, and benefits.
Start with a three-number budget
Three numbers turn a vague worry into a plan: monthly income, fixed medical premiums, and out-of-pocket medical costs. For Pat, those are $1,720 in Social Security after cost-of-living adjustments, $540 in Medicare Part B and supplement premiums for the couple, and $220 in average monthly out-of-pocket costs like prescriptions and copays. Write them on one page, top to bottom.
On its own, that page looks almost workable. Then add the $460 in property tax and homeowners insurance that survives a paid-off mortgage, and the $700 bookkeeping income Pat lost at 74. Now the page explains the tightness in the last week of the month better than any memory of the claiming decision ever will.
The next action is small and specific: take that page and call SHIP or SSA. The call works because the numbers do the talking, and the person on the other end can see the gap instead of guessing at it. If you already work with a financial adviser, bring the same three lines to that person rather than starting over with a new set of questions.
One page, three originals plus two additions, sorts the month into what repeats and what hit once. The regret question becomes a next-call question, and the parts that can still be adjusted are right there in the columns.
📞 The week after the page
Before you dial: what SHIP needs
The five lines plus the letter naming your current Part D plan. Not your tax return, not your bank statements.
The one question SSA can answer
Whether any family or survivor record applies to your household. Claiming rules are not revisited, so this is the only lever there.
Order matters
SHIP first on a weekday morning. You need the premium answer before deciding what to cut, or you cut the wrong line.
The line you don't cut
The supplement. Dropping it frees $200-ish a month and leaves the whole medical bill on a $62,000 balance.
The stopgap the page reveals
Two known hits already sitting in the ledger, $4,800 and $650, against savings of $62,000. That is the real timing problem.
Frequently Asked Questions
Can I undo claiming Social Security at 62 now that I'm 75?
Withdrawal is generally only allowed within 12 months of claiming, and suspension rules have their own age limits. At 75, the claim is almost certainly fixed. Call SSA to confirm your specific record, then focus on the budget and coverage lines that can still change.
Why does my check feel smaller even after cost-of-living increases?
The increase is applied to your early-claim base, which is lower than it would have been at full retirement age. Fixed costs like Medicare premiums, property tax, and insurance can absorb the raise before it reaches everyday spending. The raise is real; it is just small against the costs that grew.
What is SHIP and how can it help?
SHIP is the State Health Insurance Assistance Program. Counselors give free, unbiased help comparing Medicare plans and checking for extra help with premiums and copays. Bring your current plan documents and your three-number budget to the call.
My spouse died and my Social Security dropped. What do I do first?
Call SSA to confirm which survivor benefit applies to your record. Do that before cutting any care or changing your Medicare plan. The survivor benefit is based on the higher earner's record, and SSA can tell you the exact amount you are entitled to.
How do I handle a large dental or surgical bill on a fixed income?
Treat it as a savings question, not a monthly one. Ask the provider for a payment plan, check whether your Medicare Advantage or supplement plan covers any portion, and use your savings draw deliberately rather than letting the monthly budget absorb it.
Is it worth working part-time again at 75?
Only if the work fits your health and does not add costs like transport or home help that cancel the income. Remote contract work or a few hours of bookkeeping may replace some of the $700. If the job is gone for health reasons, the better move is a benefits checkup, not a job search.
Which kind of gap are you actually in?
Which kind of gap are you actually in? If it is chronic – the same shortfall every month – start with a benefits and Medicare checkup. If a health event caused it, call your State Health Insurance Assistance Program and Social Security before cutting care. If a spouse died, confirm survivor options with Social Security first.
Return to Pat's numbers: $1,720 against $540 in premiums, $220 in medical costs, $460 in housing, and the lost $700 bookkeeping income. Sorted honestly, some of that is chronic cost, some is health shock, and some – like the premium choice or a property tax relief program – may still be adjustable. The claim is fixed. The next call is not. Write down monthly income, medical premiums, and out-of-pocket costs, then make one call to SHIP or SSA. The regret over money left on the table shrinks once it becomes a list of calls you can actually make.
Write the three numbers tonight
Monthly Social Security income, Medicare premiums, and average out-of-pocket medical costs. One page, then one call to SHIP or SSA. That is the whole first step.