Getting the three years wrong costs real money: a $120,000 salary becomes $72,000, total compensation drops from about $98,000 to about $74,000, and you pay for the gap out of pocket.
The 62-year-old planning three days a week thinks it is simply five days minus two: same desk, same manager, same benefits, only prorated. The example does not cooperate.
Base pay falls to $72,000, but the 401(k) match, the bonus and the fully paid benefits go with it, and coverage changes twice before Medicare. The five-day week does not really become a three-day week until around month 14.
So treat the years as terms to be agreed, not a mood to be eased into: which days, for how long, what benefits survive, what coverage costs, which routines hold, and who owns the days off. Price them and write them down before the first reduced week, or the manager and the reorganisation will set them for you.
By the end you should be able to choose glide, stop cold, or wait, knowing which paper to get first: the coverage quote or the written schedule.
| Item | Amount | When it lands |
|---|---|---|
| Base pay reduction | $120,000 to $72,000 | Year one, when hours drop to three days |
| Total compensation drop (match, bonus, benefits) | About $98,000 to $74,000 | Year one, ongoing |
| 401(k) match | $4,800 lost | Year one, ongoing |
| COBRA health coverage | $780 per month | First 18 months after hours drop |
| Marketplace plan | $610 per month | After COBRA, until age 65 |
| Side consulting revenue | $6,000 gross, about $4,800 net | Year one |
| Commute savings | $210 per month, 90 minutes per day | Year one |
| Gym membership | $45 per month | Booked before first reduced week |
Hours drop in steps, not in a smooth line
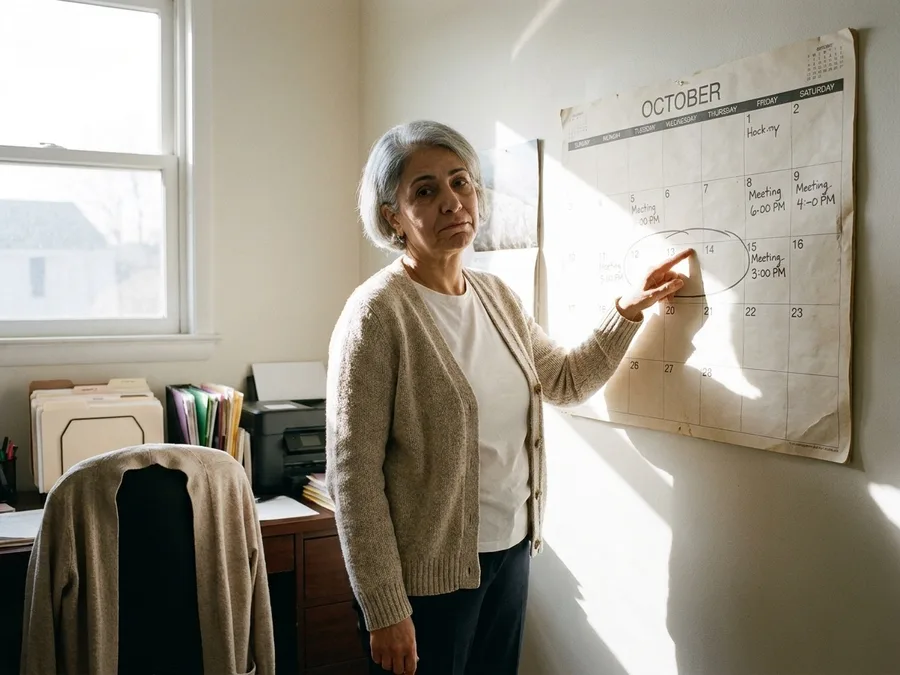
By year two the week should look like three named days and two gone ones, but almost nobody arrives there on schedule. Month one is still five days with a three-day plan attached to it.
The office keeps the title and the desk, and the meetings thin out unevenly. Tuesday and Thursday fill with the same standing calls; Monday and Wednesday disappear from the calendar while the work that used to live there gets reassigned to whoever is still in the building.
Two familiar false starts stretch the glide out. A quarterly deadline pulls the schedule back to five days for three or four weeks, then back again, and each return leaves the team unsure which days you actually cover.
That is why the written schedule needs more than your days off. Put the exact start and stop times in it, and a trigger clause: what happens to the week during a deadline, and who decides when it ends. Without the trigger, every deadline quietly sets the terms for you.
Fourteen months is the test, not the first Friday. If the calendar still shows five days at month 14, the three-day week only ever existed in conversation, and the reader has been working full time at three-fifths pay.
📆 The glide, from first ask to last day
Get the coverage quote
Price COBRA and a marketplace plan for your age before you talk to your employer.
Write the schedule down
Name the exact days off, start and stop times, duration, and who approves changes.
Book the health routines first
Put the 10 a.m. walk and the $45-a-month gym on the calendar before the first reduced week.
Hand off the accounts
Move clients, mentoring, and training into year three so the work still has a direction.
Watch month 14
If your calendar still shows five days, the glide is not the schedule you agreed to.
Set the end date
Name the day you stop completely and what comes after it, so the last year is a walk toward something.
The arrangement lives on your manager's goodwill
A phased schedule is not a benefit the company owes you, so it holds only as long as the person who agreed to it does. Nothing in the employee handbook covers it, and no one inherits the promise when your manager moves on.
In the example, a year-two reorganisation came within a week of ending the arrangement. What held it was a written exception already in the file: the days, the duration, the benefits treatment, and a named manager's sign-off. A verbal yes would have died in that meeting.
So the agreement has to spell out four things. Which days, how long the arrangement runs, what happens to benefits, and who has authority to change it. Leave any of the four blank and the missing piece resolves itself in the employer's favor.
Fit matters too. Hourly and shift roles with fixed schedules, and companies that have never run a part-time tier, rarely make this work from the start.
Timing decides the answer more than the pitch does. Asking after headcount and budget are locked turns a reasonable request into a favor against a fixed number, and a no in that window tends to stand for the year.
⚠️ COMMON MISTAKE
A verbal promise is not a written exception
If your manager says 'we'll figure it out,' that arrangement disappears the moment your manager does. Ask for the days, duration, and benefits in an email or memo — anything that human resources can find when the next reorganisation arrives.
Year three drags, because the work stops growing
The end goes flat because the work stops being new long before the salary stops. Motivation runs out ahead of the money.
In the example, the final eight months brought no fresh clients and no training. The reduced week held maintenance only, and three days of upkeep feels longer than five days of building something.
The fixes are concrete, and all of them happen early. Hand off accounts while there is still time to do it well, take on a mentoring role so the week still produces something, or move the end date forward. Trimming another day, which feels like the obvious relief, only shrinks what is left.
The tell is a month with no new work, no new client, and no training in it. When that repeats, more cutting is the wrong lever.
The first year and the last year are not the same kind of hard. Early on, you are still negotiating with the employer and the calendar keeps opening options; by the final stretch there is nothing left to negotiate, just a date to wait out, and a waiting year moves slowly.
So the test at 62 and three days is whether year three still has something ahead of you. If it does not, the end date is the thing to move, not the days.
Myths about the glide, corrected
Health coverage, not the paycheck, is the cliff
Insurance is the number that catches people off guard, and it moves twice: first the month the hours drop, then again at 65.
In the example, the first stretch runs on COBRA at roughly $780 a month for 18 months. After that a marketplace plan takes over at about $610 a month until the Medicare birthday.
The monthly figure is the easy part. Underneath it sits the doctor who quietly drops out of network, and the prescription that needs re-authorising because the formulary changed with the plan, not with the calendar.
the paperwork shows up on the plan's schedule, not the employer's last day. A letter about coverage arrives in month three, not on the Friday you hand back the badge.
The cost does not end when the job does. It ends at 65, and the stretch between the final paycheck and the Medicare card is the gap the glide opens.
Pull your own figure from the marketplace and Medicare official sites early, since what you qualify for depends on your situation and is not something this article can set for you. A quote in hand changes the whole conversation.
Glide or cold stop: what changes and what stays
Glide (three days, then out)
- Base pay falls to $72,000, total comp to about $74,000
- Health coverage gap opens early — quote before you commit
- Side work must be priced and scheduled on days off
- Social loss shows up around month six
- Success depends on a written schedule and a definite end date
Cold stop (full-time to done)
- No reduced-pay years, but no gradual loss of match or benefits
- Coverage gap still opens at your last day, not 65
- No side-work paperwork unless you choose it
- Social loss arrives all at once, not gradually
- Requires a plan for the empty Tuesday from day one
Three days a week pays less than three-fifths
Dropping to three days cuts base salary to $72,000, but the paycheck shrinks faster than that cut implies, because compensation is larger than salary.
Count the whole package and the drop is steeper: from about $98,000 down to roughly $74,000 once the match, the bonus, and fully paid benefits enter the tally.
The 401(k) match of $4,800 does not prorate with your hours. Neither does the year-two raise or the bonus, and the loss is visible the first March your statement arrives without the employer contribution.
Some benefits vanish outright instead of shrinking: life insurance, disability coverage, and in some plans tuition assistance and wellness credits. You find out at open enrollment, not at the handshake.
Before you agree to anything, put four things to HR in writing: how the match is treated, what happens to the bonus, which benefits survive at reduced hours, and what each lost item costs to replace on your own.
At 62, the number to compare is total compensation, not salary. The gap between about $98,000 and roughly $74,000 is the real annual price of the shorter week.
Side work brings its own bills and paperwork
A few clients on the side can be worth it, but the six thousand you invoice is not the six thousand you keep.
Consulting reads as found money until the first invoices land next to the first bills. In the example, roughly $6,000 comes in for year one against about $1,200 for liability insurance and software, and the quarterly tax set-aside has to be pulled out before any of it feels like income.
There is also the admin. Someone who has never invoiced anyone ends up tracking income, expenses and quarterly deadlines from the very first client, which is a part-time bookkeeping job folded into a part-time schedule.
Then the hours themselves. Side work lands on the days off, not the working days, and in the example it consumed roughly one of the three days off before anything else was scheduled into it.
Do the subtraction and the year nets closer to $4,800 before the tax set-aside, not $6,000. The net is the number that belongs in the decision, not the revenue line.
If you plan to stop work outright and owe nothing on side income, skip the calculation entirely. For that reader, a few clients is not a bridge, it is a second job.
The three-year glide at a glance
📉 Base pay
$120,000 to $72,000
💰 Total comp
About $98,000 to $74,000
🏥 Coverage
COBRA $780/mo, then $610/mo
📅 Real three-day week
Arrives around month 14
🧾 Side work net
About $4,800 in year one
The number to watch
Total compensation, not salary, because the difference between $98,000 and $74,000 is what the three-day week actually costs.
The first month feels like a cure, and then it stops
Cutting back tends to make you healthier for about four months, then it stops doing the work for you. The early returns are real, and that is exactly what sets the trap. Sleep stretches from about six hours a night to seven and a half, and the annual physical shows blood pressure down. It feels like the fix. For a while it is.
The line flattens around month four. Reduced hours fix sleep and some blood pressure, and that is close to the whole list, which is less than most people at 62 are quietly hoping for.
What held the gains in place were three unglamorous things: a fixed wake time, a standing walk, and a reason to leave the house on a day off. None of them arrive by themselves. Take the walk away and the seventh hour of sleep is the only improvement left standing.
Everything the glide does nothing about stays exactly where it was. Conditions that need treatment still need treatment, strength that needs loading still needs loading, a diet that needs changing does not change because Tuesday is free. Fewer hours are not a health plan, and the body does not read a lighter calendar as exercise.
So the measure at month four is simple. Underneath the plateau, is there a walk, a gym slot, a fixed wake time, or has the extra time just become more sitting in a better mood? The glide buys hours. What fills them is still yours to decide.
An empty Tuesday fills itself with other people's errands
It fills with errands, and mostly not your own. An empty Tuesday does not stay empty. Unscheduled days get claimed by a parent's care, by grandchildren, by the pile of house projects, and the claiming happens before you have decided anything.
In the example, a year-two caregiving stretch for a parent ate one of the three days off before anything else was on the calendar. Not planned. Absorbed.
What held were the two items booked before the first reduced week began: a standing 10 a.m. walk and a $45-a-month gym slot. Small, recurring, and already spoken for when the requests started arriving.
The commute is the quiet part of this. Dropping three office days stops costing about 90 minutes a day and about $210 a month in gas and parking, and that is time and money you can assign on purpose rather than donate by default.
Anyone whose days off are already spoken for by family does not get an empty Tuesday to design. The glide adds hours to caregiving, not freedom. Better to know that going in than to discover it in month eight.
Claim the day before someone else does, or it gets claimed.
The social loss shows up around month six
You will miss them, and you will miss them late. The daily contact goes around month six, and the strange part is that nobody notices it leaving. There is no announcement, no last day, no card. One week the hallway conversations thin out and then they are simply gone.
The office staying on your calendar two days a week hid the loss while it happened. Lunch once a month slid to twice a year without a single moment where it felt like anything had changed.
Two replacements worked, and they shared a shape: a volunteer shift and a standing class. Both scheduled, both recurring, both dependent on showing up. A vague intention to keep in touch solves none of it, because a vague intention has no calendar entry.
Missing colleagues and missing being needed are separate problems. A volunteer shift can fix the second. Only deliberate contact fixes the first, and that means picking up the phone in month two, not month ten.
The test is plain. On a day the office is closed, which relationships exist? If the answer is none, the glide has removed the daily contact and handed you back the title.
It fails when it is an escape from a job you hate
A glide only works when the job you are leaving early is a job you would keep. When it is really a way out of work you dread, three days a week carries the same dread, spread thinner over three years.
The tell is what stays on the calendar. People who cut hours to escape the meetings, the manager, the tasks that made them miserable, found all of it waiting on the days they still worked, and fewer days in between to recover.
A rough meeting on a Tuesday still ruins Tuesday and Wednesday, and now Thursday is a day off that feels like the aftermath.
Those who came through it well could name the purpose before they asked: a skill they wanted to pass on, an account handed off to a successor, a standing walk and a $45-a-month gym slot booked ahead, a parent's care worked into the week, a finish date with something attached to it.
Cutting hours and cutting the parts of the job that hurt are two different moves.
A schedule change only shrinks the calendar; it never touches the work itself, so if what wears you down is the manager or the meetings, fewer days make the bad parts denser, not lighter.
One question tells the two apart. If your hours were cut tomorrow and the job stayed exactly as it is, would you still want the three years?
A no means this is an escape and it needs a real plan, not a prorate.
A yes means the work is fine and what you need is time.
The people who would do it again changed two things
The people who came out the other side and would do it again did not have better judgment. They had gotten the fit question sorted early enough to change two things before they asked.
The first change is timing. They raised it roughly a year before they wanted to drop days, and that year is where the paperwork lives: a written schedule naming days, a coverage quote in hand, a priced list of what the benefits cut would cost.
At 62 in the $120,000 job, that means pricing the match and the fully paid benefits your base salary cut hides. Without the year, the schedule gets negotiated before anyone knows what the coverage gap charges.
The second change is depth. They went to two days, not three, because two days sets a boundary a calendar can hold; three days blurs into a full week plus a long weekend, and the off days fill with errands.
Two days is harder to pull off and easier to live inside.
What they would keep is just as telling: the gradual exit rather than a cold stop, the early handoff of accounts to a successor while they still had standing, and the health routines already on the calendar for the first reduced week.
Those two habits are what keep a careful reader from overcorrecting into quitting outright.
For a reader at 62, the sequence matters. Get the coverage quote first, then the written schedule, then have the conversation with the employer, because in that order you are negotiating terms you already understand.
Frequently Asked Questions
Can my employer refuse a phased retirement request?
Yes, in most cases. Unless your contract or a union agreement says otherwise, a reduced schedule is a discretionary arrangement, not a right. That is why you need the days, duration, benefits, and approval process in writing — a verbal yes from your manager can disappear in the next reorganisation.
How much does health coverage really cost between 62 and 65?
In the example, COBRA is about $780 a month for 18 months, then a marketplace plan about $610 a month until the Medicare birthday at 65. Your own quote depends on your age, location, and plan choice. Get it from the marketplace and Medicare official sites before you agree to any schedule change.
Will cutting back to three days actually improve my health?
It can improve sleep and some blood pressure readings — in the example, sleep went from about six hours a night to seven and a half, and the annual physical showed blood pressure down. But the improvement flattens around month four. What carries it forward is a fixed wake time, a standing walk, and a reason to leave the house on a day off.
What is the biggest mistake people make with a phased retirement?
Agreeing to the schedule before pricing the coverage gap and the lost benefits. Total compensation falls further than base pay because the 401(k) match, bonus, and fully paid benefits do not scale down — they vanish. Get the coverage quote first, then the written schedule, then make the ask.
How do I know if a phased retirement is right for me?
Ask yourself one question: if the hours were cut tomorrow and the job stayed exactly the same, would I still want the three years? If the answer is no, the glide is an escape from a job you hate, and the same problems will follow you into three days a week. If the answer is yes, write down what the three years are for before you ask.
The coverage quote, then the schedule, then the ask
The choice depends on your situation, so make it outright. Glide if your coverage and calendar are already sorted. Stop cold if the job itself is the problem or the employer will not commit anything to writing, because a verbal promise is not an arrangement and three years is a long time to stretch out a job you dread.
Get one document before you discuss a single day: the coverage quote or the written schedule. Price COBRA at about $780 a month for 18 months and a marketplace plan at about $610 until 65. Without one of those, the glide is a favor someone can withdraw.
You walked in believing three days a week would be five minus two, same desk, only prorated. The days, the money and the coverage do not settle themselves; they get settled by whoever writes them first, so put the quote or the schedule on the table before the first reduced week and do not sign away the days without it.
Get the coverage quote before you agree to anything
Before your next conversation with your employer, price the gap: COBRA and a marketplace plan at your age. Then put the days, duration, and benefits in writing. That is the order that protects you.