A new tax law just landed, and it reshapes the math for anyone retired or closing in on it. The One Big Beautiful Bill Act, OBBBA for short, is big enough that even careful readers are missing pieces of it.
This is not about politics. It is about which deductions you can actually take, which ones expire, and where a phaseout can quietly take back part of the break.
The headline items are the permanent lower rates and the bigger standard deduction. The ones that trip people up are the new senior bonus, the car-loan interest break, and the higher SALT cap, because all three come with deadlines.
Below you get the ten changes that matter most for retirees, in plain language, with the numbers attached. By the end you will know which ones to use now and which ones to put on the calendar.
Quick Tips Before You Start
Know your taxable income
That is gross income minus deductions, not your Social Security check or IRA withdrawal by itself.
Mark the sunset dates
The senior bonus ends after 2028, car-loan interest after 2028, and the higher SALT cap after 2029.
Watch the phaseouts
Extra income can shrink a deduction, so a raise or Roth conversion may cost more than the bracket rate suggests.
Keep every receipt
Charitable cash gifts and car-loan interest both need documentation when you file.
Verify with the IRS
Rules can change, and the IRS worksheets are the final word on phaseout math.
1. Lower Tax Brackets Are Now Permanent
Picture yourself in January, tax software open, wondering whether the rate you are entering is about to change on its own after 2025. It is not. Back in 2017, the Tax Cuts and Jobs Act trimmed most bracket rates by 3 or 4 percentage points, and those lower rates were written to expire at the end of 2025, which is why so many retirement plans were built around pulling income forward before they vanished.
OBBBA makes those lower rates permanent. Permanent here does not mean frozen forever. It means no automatic snap-back on a set date. Congress would have to pass new legislation to change them.
That matters for planning because the old deadline for Roth conversions is gone. You no longer have to rush a conversion into 2025 to beat an expiration that is not coming. You still want to convert in the years when it costs you least, so check your marginal rate against next year's before deciding, and remember that a future Congress can always change the rules.
💡 Tip: Permanent is a legal term, not a promise. Build your plan so it still works if rates move later.
2. A $100,000 Couple Pays $11,157
The bracket rates sound abstract until you see them applied to a real number. Take a married couple filing jointly with $100,000 of taxable income.
The first $23,850 is taxed at 10%, which comes to $2,385. The next slice, up to $96,950, is taxed at 12%, adding $8,772. The remaining $3,050 lands in the 22% bracket and adds $671.
Add those three pieces and you get $11,157. That is the actual federal income tax on that $100,000, not 22% of the whole thing. The 22% rate applies only to that last sliver, and the average rate works out to about 11%.
One reminder: taxable income is what is left after deductions. Your gross Social Security, pension, and IRA withdrawals are higher than the number you plug into the brackets, so line up your deductions first – the next one hands you a big piece of that math.
| Provision | Maximum amount | Phaseout starts | Timing |
|---|---|---|---|
| Lower tax brackets | 3–4 points off most rates | None | Permanent |
| Standard deduction | $15,750 single / $31,500 married | None | Permanent |
| 65+ add-on | $2,000 single / $1,600 per married person | None | Permanent |
| Senior bonus deduction | $6,000 single / $12,000 married | $75,000 single / $150,000 married | Expires after 2028 |
| Charitable cash deduction | $1,000 single / $2,000 married | None | Starts 2026, permanent |
| New-car loan interest | $10,000 | $100,000 single / $200,000 married | 2025–2028 purchases |
| SALT cap | $40,000 | $500,000 single or married | Expires after 2029 |
| Tips and overtime | $25,000 tips / $12,500–$25,000 overtime | $150,000 single / $300,000 married | 2025 onward |
3. Standard Deduction Gets Bigger and Permanent
Because taxable income is what the brackets touch, the deductions that get you there carry as much weight as the rates themselves. The 2017 law nearly doubled the standard deduction, that change was also set to expire, and OBBBA makes it permanent for 2025 at $15,750 for single filers and $31,500 for married filing jointly, up slightly from the prior year.
The existing 65-and-older add-on survives too: $2,000 for a single filer and $1,600 for each married person who is 65 or older. That piece is separate from the new senior bonus, and it comes before it in the math.
💡 PRO TIP
Stack the 65+ breaks in order
Regular standard deduction first, then the 65+ add-on, then the senior bonus. Getting the order right is what shows a couple both 65+ reaching $46,700.
4. New $6,000 Senior Bonus Has a Catch
Starting in 2025, taxpayers 65 and older get a bonus deduction of $6,000 if single or $12,000 if married filing jointly, on top of the regular standard deduction and the 65+ add-on.
For a couple where both spouses are 65 or older, that stacks to $31,500 plus $3,200 plus $12,000, or $46,700 of standard deduction before any phaseout. For many retirees that is enough to wipe the tax off Social Security benefits. It is not a literal, blanket exemption for Social Security, so do not expect the balance of every retirement dollar to reset.
The catch is the phaseout and the clock. The bonus starts shrinking at $75,000 of income for single filers and $150,000 for married filing jointly, and it disappears entirely after 2028. If your income sits near either line, run the IRS worksheet before you count on the full amount.
5. Phaseouts Can Raise Your Effective Tax Rate
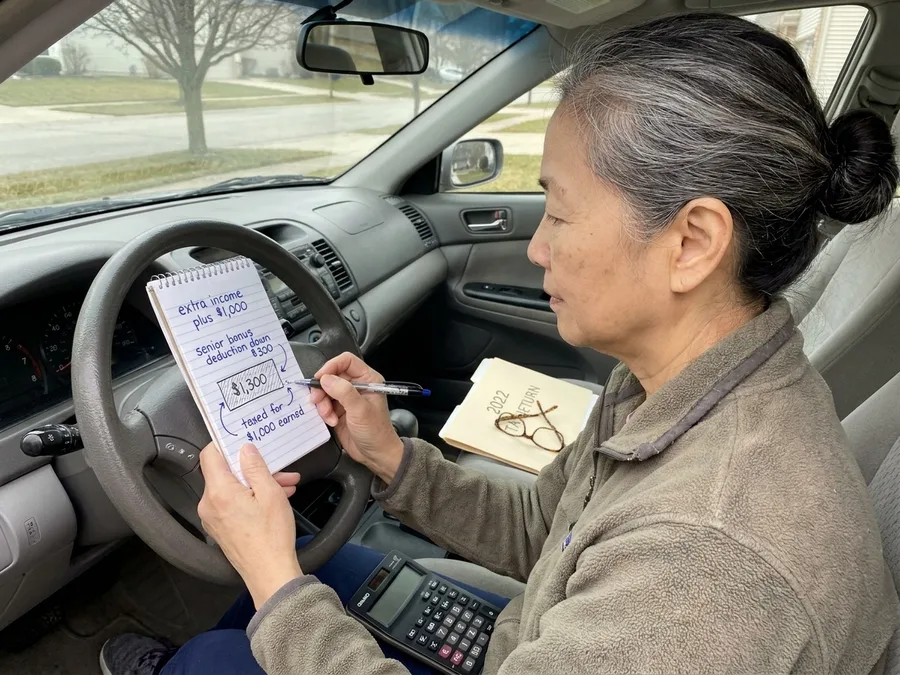
That phaseout is why your effective rate can outrun your bracket. Say you earn $1,000 more this year, and that extra $1,000 costs you $300 of the senior bonus deduction. You effectively pay tax on $1,300 for $1,000 of new income – a higher rate than the bracket chart shows.
That gap is the difference between your marginal bracket rate and your marginal effective rate. The senior bonus, car-loan interest, tips and overtime, and the SALT cap each have their own phaseout ranges, and each one bites at a different income level. Before a raise, a Roth conversion, or a capital gain, model it: take last year's return, add the extra income, and check the phaseout formula on the IRS worksheet.
6. Charitable Cash Deduction Works Without Itemizing
That is exactly why this next break exists. Starting in 2026, single filers can deduct up to $1,000 of cash charitable gifts, and married couples filing jointly up to $2,000, even when they take the standard deduction.
It is an above-the-line deduction, so there is no income threshold and no itemizing hurdle to clear. It is also permanent, which makes it one of the few breaks you can count on without a sunset date.
Keep the receipts and the acknowledgment letters. Non-cash donations like clothes or furniture do not fit this break; if you itemize, your charitable gifts follow the regular rules instead.
A quick example: a retired couple gives $150 a month to their church, about $1,800 a year. Under the new rule they can deduct the whole $1,800 on top of the standard deduction, no itemizing needed.
7. New-Car Loan Interest: Up to $10,000
Unlike the permanent rate changes, this one comes with a clock. If you buy a new car between January 1, 2025, and December 31, 2028, you may be able to write off as much as $10,000 in interest on the loan, limited to one vehicle per taxpayer each year.
The rules are strict. The car must be new, not used, and its final assembly must be in the United States. Leases are outside this break entirely, so a lease payment does not count no matter how the dealership frames it.
Then comes the phaseout: the deduction starts shrinking at $100,000 of income for single filers and is gone by $150,000, while for married filing jointly it starts at $200,000 and ends at $250,000.
Keep the lender's interest statement, the purchase date, the VIN, and documentation of final assembly. Check the IRS guidance for the exact paperwork before you buy.
As an example, a couple with $60,000 of income who pays $6,000 of interest on a U.S.-assembled new car can deduct the full $6,000.
8. SALT Cap Jumps to $40,000 — Temporarily
That itemizing hurdle comes back around here. The state and local tax deduction, or SALT, covers state income or sales tax plus local property tax. Under the 2017 law it was capped at $10,000, a real pinch for retirees in New York, California, or Massachusetts where property taxes alone can run into the tens of thousands.
OBBBA raises the cap to $40,000. It phases out starting at $500,000 of income for both single and married filing jointly, and it expires after 2029.
One thing to keep straight: the higher cap only helps if you itemize. Retirees living on investment income still need to clear the standard deduction before SALT gives them anything.
Permanent vs. Temporary Breaks
Permanent
- Lower bracket rates
- Bigger standard deduction
- 65+ add-on
- Charitable cash deduction (from 2026)
Temporary
- Senior bonus deduction (ends after 2028)
- New-car loan interest (purchases through 2028)
- SALT cap at $40,000 (ends after 2029)
9. Tips and Overtime Get Above-the-Line Deduction
At the end of a long shift, the last thing you want is a tax surprise on the tip money you counted. Under OBBBA, workers can deduct 100% of tips, capped at $25,000 for each tipped worker in the household, plus overtime up to $12,500 for single filers or $25,000 for married filing jointly.
Both are above-the-line, effective for 2025, so you do not need to itemize. The phaseout starts at $150,000 for single filers and $300,000 for married filing jointly.
If you are self-employed or doing gig work, do not assume your payments count as tips or overtime. Check the definitions in the IRS guidance before you claim either one.
Five Steps to Take Before You File
10. Most Retirees Pay Less — If They Plan
For most people, smaller tax bills for the next several years. But getting the most out of it means knowing your current and future tax picture and timing your income to match.
The permanent pieces, lower rates, the bigger standard deduction, and the charitable break, are the foundation. The temporary ones, the senior bonus, the car-loan interest, and the higher SALT cap, need to be used before their dates pass, and the phaseouts scattered across all of them need checking every year.
There is more in OBBBA that this list does not touch, including Trump accounts, scholarship donation credits, the child tax credit, adoption credit changes, HSA changes, and small business provisions. For those, go to the IRS or a tax planner who can look at your whole picture.
Roth Conversions Need a New Timing Check
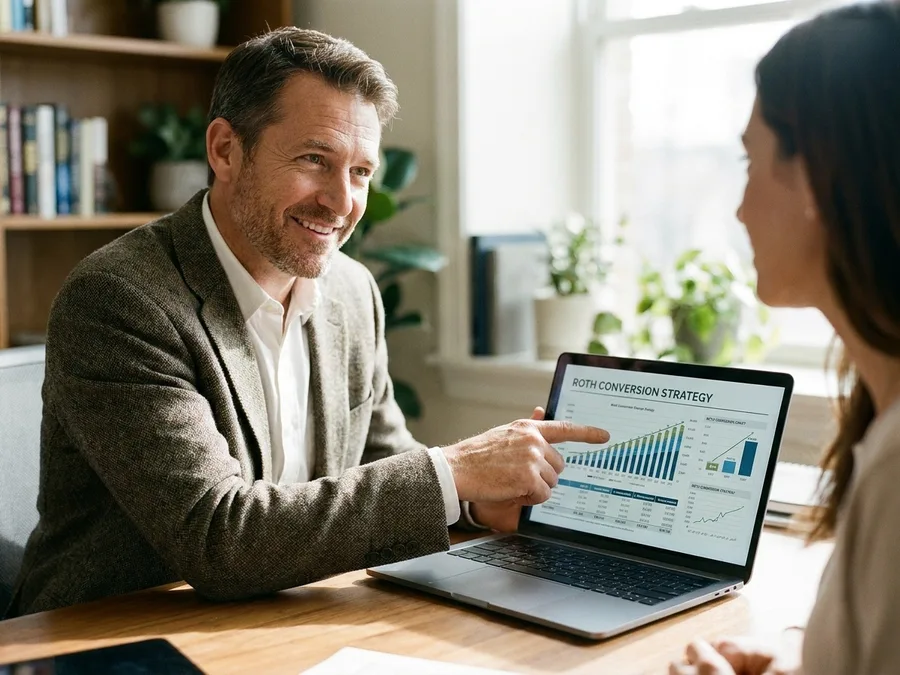
Here's a shift a lot of retirees haven't caught up with. For years, the advice was to convert to a Roth before the lower rates vanished. Now those lower rates are permanent, so that particular clock stopped ticking.
Permanent just means Congress has to act again to change the rates. It does not mean you should rush a conversion into any one year to beat a deadline that isn't coming.
So how does a conversion actually work against you? It adds taxable income. That extra income is counted when the IRS tests whether you're over the phaseout lines.
Cross $75,000 single or $150,000 married, and the $6,000 senior bonus starts shrinking. Push higher and you can clip the new-car loan interest deduction, the tips and overtime breaks, or the SALT cap.
Here's the catch most people miss. The deduction you lose can cost more than the conversion saves. A $20,000 conversion might save you a few thousand in future tax but knock $3,000 off a deduction you were counting on this year.
That's the math to run. Sometimes stopping just below a phaseout beats a larger conversion, even at the same bracket rate.
Get a written tax projection before you convert. Ask your preparer to show the tax at your planned amount, then at a smaller one that stays under the nearest threshold, side by side.
Then recheck the law every year. Permanent doesn't mean frozen.
Put Each Expiration Date on the Calendar
If the Roth point made one thing clear, it's that timing now matters more than urgency. The breaks don't all end at once, and mixing up the dates is how people lose money they thought was locked in.
Three of them have hard ends. The senior bonus deduction expires after 2028. The new-car loan interest break only covers cars bought through December 31, 2028. The higher $40,000 SALT cap runs out after 2029.
The permanent items are the lower rates, the standard deduction, the 65+ add-on, and the 2026 charitable deduction for cash gifts.
For each temporary break, do one comparison. What is it worth to you in an eligible year, against what it costs to delay that income or that purchase until the year lines up? A $10,000 car-loan interest deduction at 22% is $2,200 back. That's worth planning a purchase around.
Set calendar reminders for each date now, while it's fresh. One for the end of 2028, one for the end of 2029.
And verify the current law before you act on any of them. Congress can change permanent and temporary rules alike, so a yearly check against the IRS or with a tax planner keeps your plan honest.
Frequently Asked Questions
Does the senior bonus really make my Social Security tax-free?
Not literally. It gives you an extra deduction of $6,000 single or $12,000 married filing jointly, which for many retirees reduces taxable income enough that Social Security benefits fall below the threshold. But the bonus phases out starting at $75,000 single and $150,000 married filing jointly, and it expires after 2028. Run the IRS worksheet to see your exact number.
Is the $40,000 SALT cap permanent?
No. The higher cap applies through 2029 and then expires unless Congress acts. It also phases out starting at $500,000 of income for both single and married filing jointly. And it only helps if you itemize, so many retirees taking the standard deduction will not benefit from it at all.
Can I deduct interest on a used car or a lease?
No. The new-car loan interest deduction applies only to new cars with final assembly in the United States, purchased between January 1, 2025, and December 31, 2028. Used cars and leases are outside the break. It is limited to one car per taxpayer per year and phases out at $100,000 single and $200,000 married filing jointly.
Do I need to itemize to get the charitable deduction?
No. Starting in 2026, the charitable cash deduction is above-the-line, so you can take it even when you claim the standard deduction. The limit is $1,000 single or $2,000 married filing jointly, there is no income threshold, and it is permanent. Non-cash gifts do not qualify for this particular break.
What counts as tips and overtime for the new deduction?
The deduction covers up to $25,000 of tips per tipped worker and up to $12,500 single or $25,000 married filing jointly of overtime, effective for 2025. It phases out starting at $150,000 single and $300,000 married filing jointly. Self-employed and gig workers should check the IRS definitions before claiming either, because not every payment counts as tips or overtime.
Which Sunset Date Lands on Your Calendar First
If you are 65 or older and comfortably under the phaseouts, stack the deductions and check the 2028 sunset for the senior bonus. That is your biggest single break, and it has the earliest deadline.
If your income sits near a phaseout line, model a Roth conversion or a raise before you take it. The effective rate can be higher than the bracket chart suggests, and the IRS worksheet will show you the real cost.
If you are planning a big purchase, compare the car-loan window against the SALT cap timeline. Both are temporary, and both reward acting while they are open.
Put the earliest expiration date on your calendar and verify the rules with the IRS or a tax planner before you file.
Check Your Phaseout Before You File
Look up last year's taxable income and see which of these breaks you can still claim. Then mark the 2028 and 2029 sunset dates where you will actually see them.